Why insurance needs a dedicated accounting and financial operations platform.
Insurance money is complicated. Behind every premium and claim sits a web of payments, commissions, reconciliations and financial obligations that need to be managed, tracked and accounted for.
Insurance accounting isn't accounting with an insurance label on it
Consider what happens when someone pays an insurance premium.
That single payment can involve a broker, an underwriting agency, one or more insurers and potentially several other parties. There are commissions to calculate, taxes and levies to account for, different settlement arrangements and financial records to maintain.
The money and information needed to account for it often don't arrive together.
A payment might land in a bank account days or weeks before the remittance information needed to identify it. One payment might cover multiple policies, insurers or accounting periods. Each party has its own systems, processes and reporting obligations.
Someone has to work out what's been paid, what it relates to, who is owed and where the money needs to go.
Now multiply that by thousands of transactions, across different products, businesses, currencies and markets and it's easy to see why insurance finance teams have their work cut out for them.
The gap between the systems
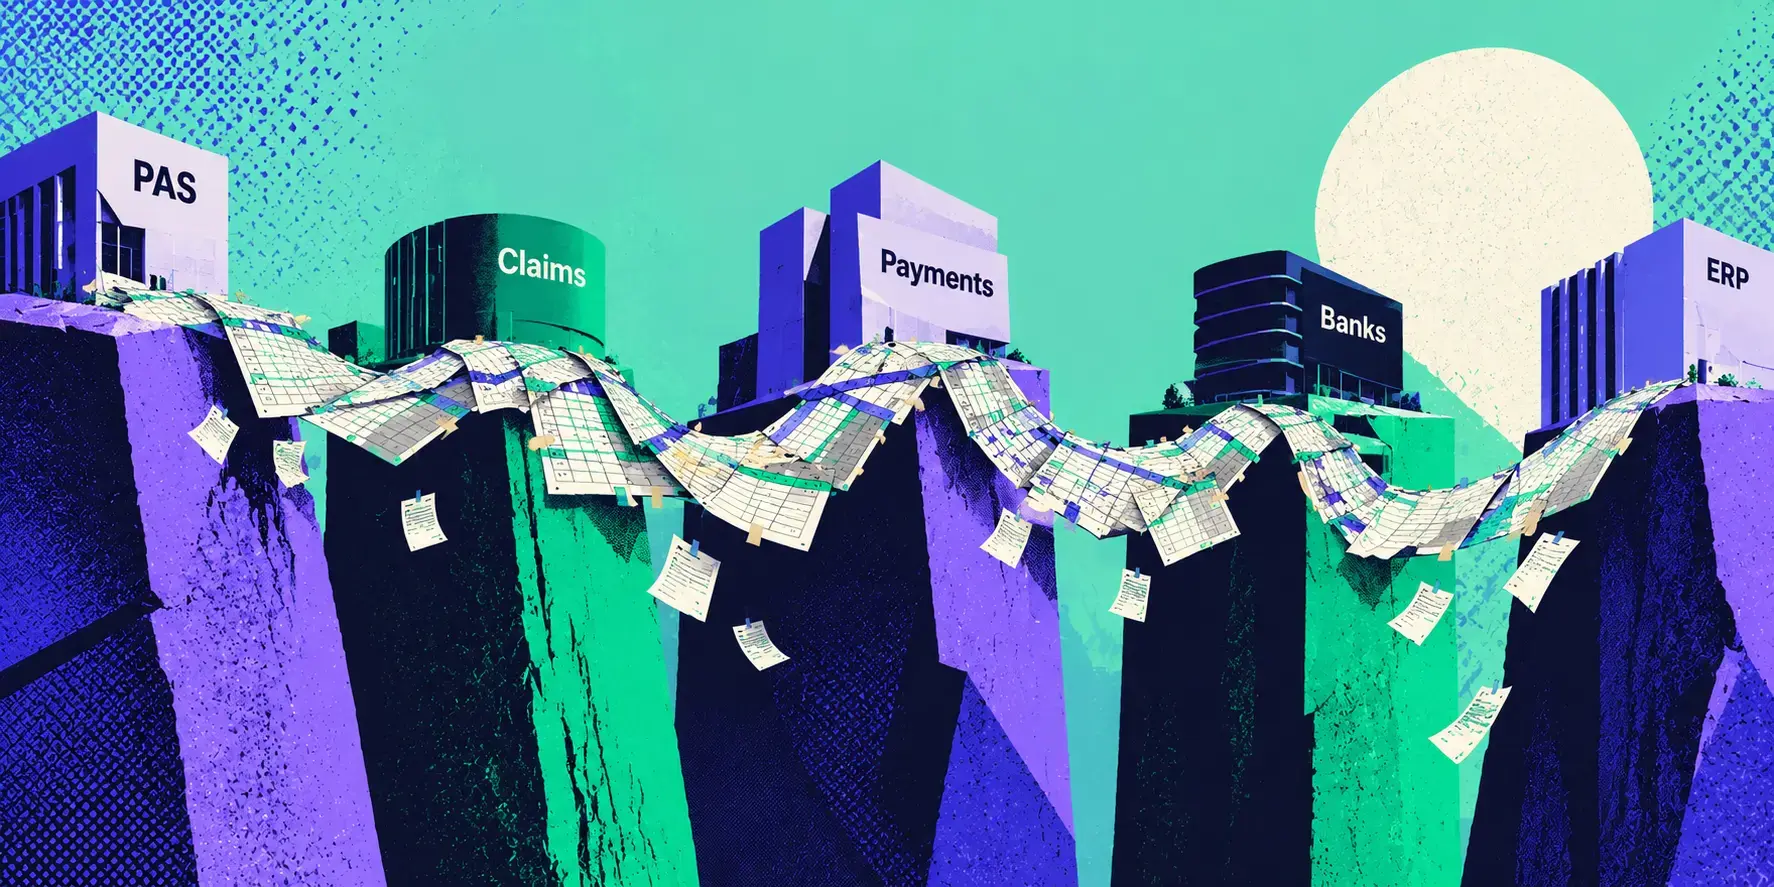
Most insurance businesses already have plenty of technology. Policy administration systems manage policies. Claims systems manage claims. Payment providers process payments. Banks hold the money. ERPs manage the wider business finances.
Each does its own job. But the financial work that happens between these systems is where things fall through the gaps.
Payments need to be matched to policies and claims. Commissions, taxes and other obligations need to be calculated and allocated. Money needs to be reconciled, accounted for and settled between parties.
And because these systems don't always share information in the same way or at the same time, finance teams are left plugging the gaps with spreadsheets, manual workarounds and a lot of chasing.
For businesses growing through acquisition, the challenge gets bigger. Each new business can bring another policy system, another set of bank accounts and another way of doing things.
From the outside, it's one group. Under the hood, it can be anything but.
Making the complicated stuff simple
A dedicated insurance accounting and financial operations platform takes care of the financial work that sits between these systems.
It connects payment, policy, claims, banking and remittance information, then applies insurance-specific rules to match transactions, calculate obligations and manage the accounting and settlement processes that follow.
Much of this work can happen automatically, with finance teams stepping in when something needs investigating or a decision. And because the information is reconciled continuously, teams have a clear picture of what's been paid, what's outstanding, what they owe and what's still to be settled.
That same information supports the wider financial work, from debtor and creditor management to premium and claims accounting, recoveries, trust accounting, bordereaux, reporting and month-end close.
The important thing is that the information carries through these processes without people having to repeatedly extract, check and re-enter it. And businesses can keep using the policy, claims and accounting systems they already have.
For insurance groups with multiple businesses, this means they can establish consistent financial processes and reporting across the group without having to move everyone onto the same technology.
Growth has a habit of making financial complexity worse
More policies mean more transactions. New products bring different accounting requirements. Acquisitions introduce more systems, bank accounts and ways of working.
If the underlying processes remain manual, finance’s workload grows with the business.
That's a problem when you're trying to scale without continually adding people to manage the extra work.
With the right technology in place, insurance businesses can grow without continually adding finance headcount. Finance teams gain near real-time visibility of cash and financial obligations, reduce unallocated cash and credit exposure, strengthen financial controls and cut weeks from month-end close.
For groups growing through acquisition, new businesses can be brought into established financial operations without having to replace their existing systems.
What does that look like in practice?
At Grappler, we've seen how much difference this can make. Delta Insurance reduced its month-end close from four weeks to one, giving its finance team a near real-time view of cash and settlement positions.
Another customer reduced unallocated cash from approximately $20 million to $400,000, a 98% reduction.
We've also seen customers manage two to three times more premium volume without adding finance headcount. One insurer doubled its ledger, expanded into new markets and introduced new products without needing additional finance staff.
These improvements come from taking the repetitive financial work off people's hands and giving them reliable information to work with.
And the benefits extend beyond the finance team. When businesses have a clearer picture of their cash and financial obligations, they can make decisions sooner, respond to problems earlier and grow with greater confidence.
Built for the way insurance works
Insurance will always involve complicated financial relationships. Different parties, systems, obligations and settlement arrangements are part of how the industry operates. But managing that complexity shouldn’t mean more spreadsheets, more manual work and more people chasing numbers.
A dedicated insurance accounting and financial operations platform gives finance teams the tools to manage this complexity as part of their everyday work.
So as the business grows, finance can spend less time keeping up and more time helping it move forward.
If you're looking to reduce manual work, get a clearer picture of your cash position and grow without adding to your finance team, take a look at Grappler.
Recognised as one of the world's most innovative InsurTech companies in 2026, Grappler is purpose-built to make the complicated financial work behind insurance a whole lot easier.
Get in touch and see what Grappler can do for your business.